Kampala: Uganda is sitting on an estimated 500 million tonnes of iron ore underground, a mineral endowment that could fundamentally transform the country’s industrial base if it is commercially mined, beneficiated and converted into iron, steel and higher-value manufactured products for the East African market.
But according to EABC Board Director Oscar Kamukama, the real opportunity is not simply to extract the ore.
It is to turn Uganda’s underground mineral wealth into above-ground industrial wealth and build a steel industry designed for East Africa.
Kamukama, who doubles as Business Development Manager at Steel & Tube Industries Ltd, says Uganda must move decisively from a mineral-exporting economy towards an integrated iron and steel value chain capable of supplying the region’s rapidly growing infrastructure, construction, energy, manufacturing and housing sectors.
“Let us build a unified Ugandan industrialisation story, one that begins with Ugandan iron ore, moves into Ugandan processing, produces Ugandan iron and Ugandan steel, transforms into value-added Ugandan fabricated products, and directly powers national and regional infrastructure projects.”
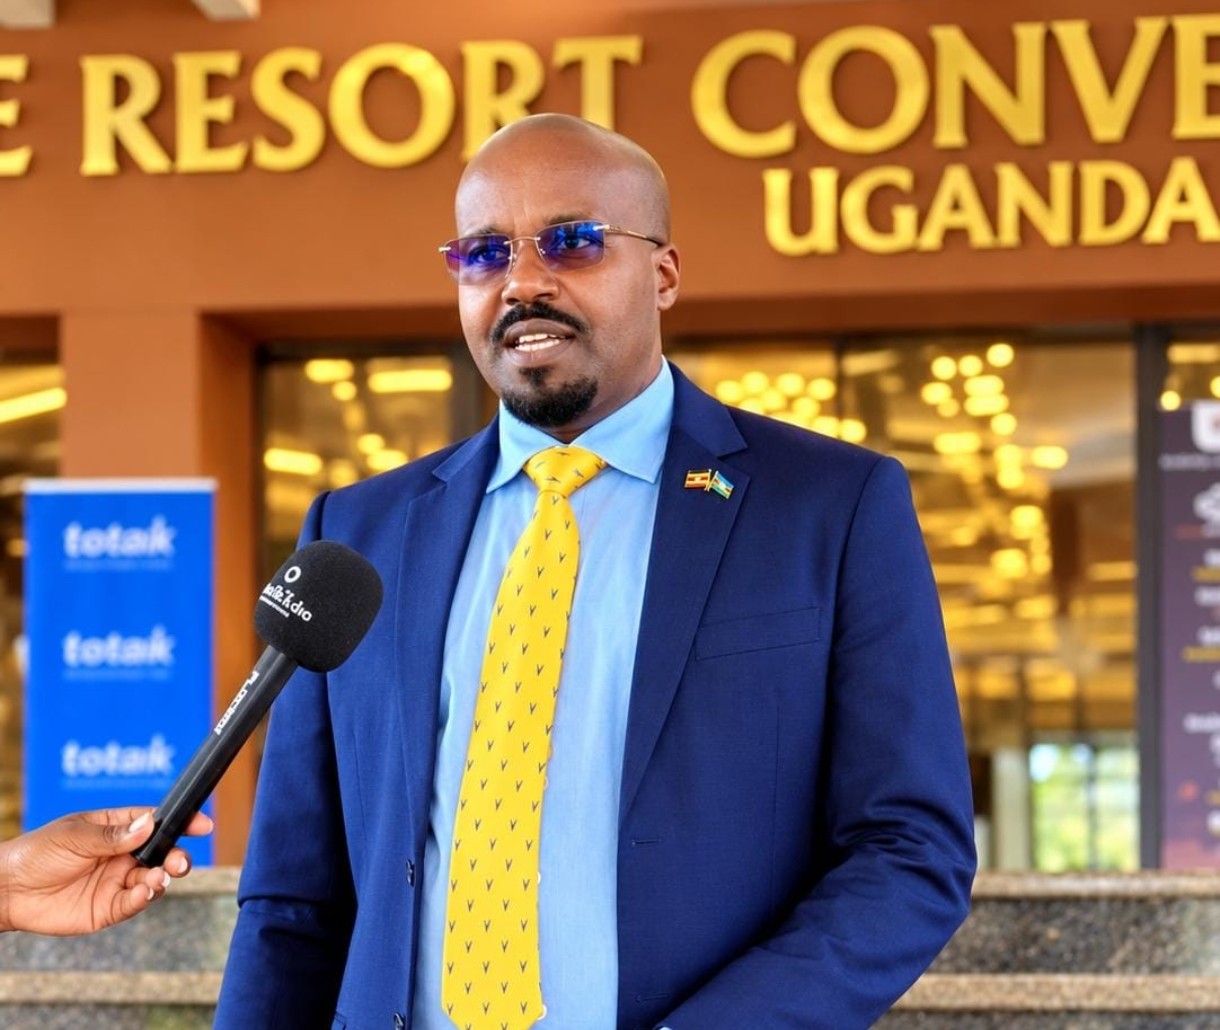
He made the remarks during the 15th Annual Mineral Wealth Conference and Expo 2026, held at Speke Resort Munyonyo in Kampala from September 29–30.
500 MILLION TONNES: FROM UNDERGROUND WEALTH TO INDUSTRIAL WEALTH
Kamukama said Uganda’s iron ore deposits should no longer be viewed simply as geological resources waiting to be extracted.
They should be viewed as the potential foundation of a major industrial ecosystem.
The opportunity stretches far beyond mining:
Iron ore → beneficiation → ironmaking → steelmaking → billets → rolled steel → fabricated products → infrastructure → regional exports.
“If we have the ore underground but continue importing substantial quantities of industrial steel products, then we have not fully captured the economic value of our mineral wealth,” Kamukama argued.
The objective, he said, should be to ensure that a growing proportion of the value created from Uganda’s iron ore is captured inside Uganda through processing, manufacturing, employment, technology transfer, industrial investment and exports.
EAST AFRICA SHOULD BE THE MARKET
As an EABC Board Director, Kamukama said Uganda must think beyond the limits of its domestic market.
The East African Community should be regarded as Uganda’s immediate strategic market for industrial products.
The region’s growing population, urbanisation, infrastructure requirements and expanding manufacturing base are creating long-term demand for steel.
“This is the market Uganda must be thinking about,” Kamukama said.
“We should not build an iron and steel industry whose ambition ends at the Ugandan border. We must build an industry that can competitively supply East Africa.”
Uganda’s geographical position gives it access to major markets across Kenya, Tanzania, Rwanda, Burundi, South Sudan, the Democratic Republic of Congo and Somalia, while the wider Great Lakes region offers additional opportunities.
The implication is significant: Uganda does not have to consume all the steel it produces.
It can manufacture for the region.
THE STEEL MARKET IS BIGGER THAN UGANDA
Kamukama said the case for investment in integrated steel making becomes stronger when Uganda looks at the combined regional market rather than domestic consumption alone.
The EAC’s Seventh Development Strategy for 2026/27–2030/31 places the regional population at more than 341 million people.
That population represents demand for:
– Roads and bridges
– Railways and transport infrastructure
– Housing
– Industrial parks
– Energy projects
– Oil and gas infrastructure
– Commercial buildings
– Water infrastructure
– Manufacturing facilities
– Agricultural infrastructure
All require steel.
“The question is not whether there will be demand,” Kamukama said.
“The question is whether Uganda will position itself to supply that demand competitively.”
FROM ORE TO FINISHED PRODUCTS
Kamukama said Uganda’s ambition should not stop at producing iron ore concentrate or even billets.
The country should progressively develop the capacity to manufacture increasingly sophisticated steel and fabricated products.
Beneficiated iron ore can feed ironmaking and steel making operations, producing billets that can subsequently be transformed into products such as reinforcement bars, hollow sections, angle bars, round bars and other structural and fabricated steel products.
That creates multiple layers of economic activity — from mining and processing to manufacturing, construction and regional trade.
For Uganda, he said, this means more jobs, more industrial capacity, more tax revenues, more exports and greater participation in regional supply chains.
UGANDA MUST COMPETE — NOT JUST PRODUCE
Kamukama cautioned that having hundreds of millions of tonnes of iron ore does not automatically make Uganda a steel power.
The country must develop a competitive ecosystem around the mineral.
This includes:
Affordable and reliable energy.
Modern technology.
Efficient logistics.
Competitive transport costs.
Access to long-term financing.
Economies of scale.
Quality standards.
Skilled human capital.
Predictable industrial policy.
“The question is not whether Uganda has iron ore,” Kamukama said.
“The question is whether we can convert that ore into competitively priced, quality steel and move it efficiently into the EAC market.”
That, he said, should be one of the central questions confronting policymakers, investors, financiers and manufacturers.
FROM UGANDA’S INFRASTRUCTURE TO EAST AFRICA’S INFRASTRUCTURE
Kamukama said Uganda’s own infrastructure programme provides an important anchor market, but the long-term ambition should be regional.
A strong domestic steel industry could supply Uganda’s infrastructure while simultaneously developing the scale and competitiveness required to export.
This creates what he described as a potentially powerful industrial cycle:
Ugandan minerals → Ugandan processing → Ugandan steel → Ugandan manufacturing → Ugandan infrastructure → EAC exports.
“The EAC gives us the immediate regional market, while AfCFTA gives us the continental horizon,” he said.
«Our objective should be to manufacture in Uganda, create value in Uganda and export from Uganda to the region and Africa.”
EAC INTEGRATION MUST MEAN INDUSTRIAL INTEGRATION
As a member of the East African Business Council (EABC) Board, Kamukama said regional integration should increasingly be measured not only by the movement of goods, but by the development of regional value chains.
Uganda should therefore seek to participate in regional industrial supply chains rather than simply remaining a market for finished products manufactured elsewhere.
A competitive Ugandan steel industry could supply construction and manufacturing businesses across the EAC, while regional infrastructure projects could provide the scale necessary to support further investment in production capacity.
This, he said, would turn regional integration into a practical industrial strategy.
FROM MINERAL WEALTH TO INDUSTRIAL POWER
Kamukama said Uganda’s mineral wealth must ultimately be judged by what it produces for the economy.
The objective should not simply be to say that Uganda has hundreds of millions of tonnes of iron ore underground.
The real achievement would be to say:
Uganda mined it.
Uganda processed it.
Uganda made the iron.
Uganda made the steel.
Uganda manufactured the products.
Uganda built its infrastructure.
And Uganda exported the surplus to East Africa and Africa.
For Steel & Tube Industries, Kamukama said participation in the Mineral Wealth Conference was an opportunity to place manufacturers at the centre of Uganda’s mineral-value-addition conversation.
“The time for summits, forums and workshops must now translate into action. We need to get the minerals out of the ground, process them here, manufacture here and build the regional markets that will sustain the industry.”
He said Uganda should now begin thinking seriously about an East African steel strategy — one that connects mineral exploration and beneficiation with manufacturing, infrastructure, regional trade and export competitiveness.
The opportunity, Kamukama said, is no longer simply to have iron ore beneath Uganda’s soil.
It is to build an industrial powerhouse above it — and make Uganda a competitive steel supplier to East Africa and the wider African market.