Tag: Christopher Legilisho

  • Private sector ends 2025 with high hopes for further expansion in 2026

    Private sector ends 2025 with high hopes for further expansion in 2026

    Expansions in output and new orders sustained

    Employment broadly unchanged on the month

    Higher input costs spur further rise in output charges

    Following  a ten-month period of job creation, Ugandan companies saw a broad stagnation in employment levels and higher input costs during December, nonetheless driven by other factors, the monthly Stanbic Purchasing Managers Index (PMI) rose slightly to 54.0 compared to the 53.8 recorded for November 2025.

    Readings above 50.0  signal an improvement in business conditions on the previous month, while readings below 50.0 show a deterioration.Like much of 2025, business conditions continued to improve amid sustained expansions in output and new orders.

    Meanwhile, input price inflation was sustained as purchase costs rose further. Prevailing demand conditions enabled firms to increase selling prices. The December data indicated an eleventh successive monthly improvement in business conditions.

    According to the latest survey, firms were also upbeat regarding the outlook for output in the coming year, which spurred greater input buying and efforts to build stocks. That said, businesses signalled broadly unchanged employment levels.
    Christopher Legilisho

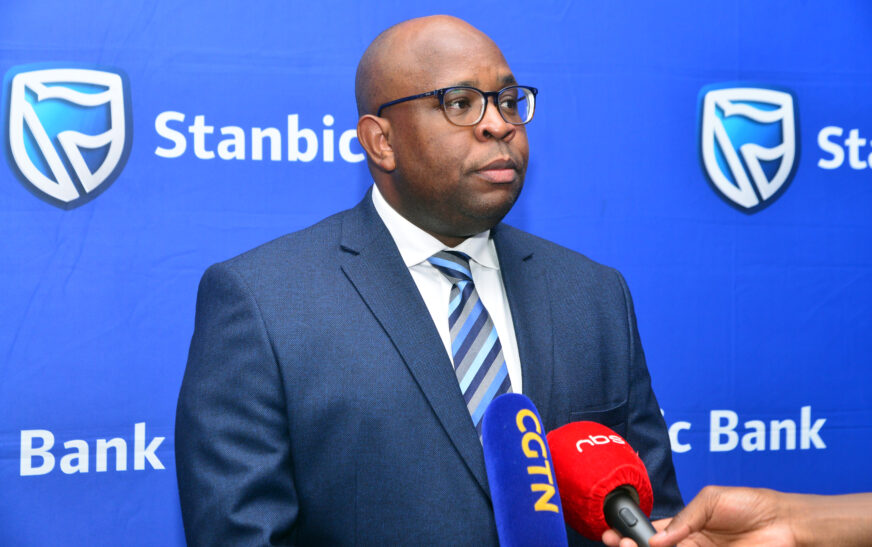
    Christopher Legilisho, Economist at Stanbic Bank said, “Conditions in Uganda’s private sector were upbeat as the Stanbic Purchasing Managers Index (PMI) remained in expansion territory in December, implying that strong consumer demand conditions drove new orders and boosted output in the private sector. The state of employment was healthy, with staffing levels broadly steady following a ten-month period of growth, while backlogs mounted due to capacity pressure from increasing orders. This was evident in further expansions in quantities purchased and inventories held by Ugandan firms.”

    The Stanbic PMI is compiled by S&P Global from responses to questionnaires sent to about 400 purchasing managers. The sectors covered by the survey include agriculture, mining, manufacturing, construction, wholesale, retail and services. The index is a weighted average of the following five indices: New Orders (30%), Output (25%), Employment (20%), Suppliers’ Delivery Times (15%) and Stocks of Purchases (10%). Legilisho said, “The rise in input prices was linked to elevated water and electricity costs in December. Purchase prices also increased due to concerns about construction costs, among other factors. Wage costs were broadly flat, while output prices increased due to robust customer demand.

    On the whole, this suggests that the economy is performing briskly, which should be confirmed when official growth data is released.”Greater new orders reportedly drove the latest expansion, with new sales increasing on a continuous basis since February 2025. Anecdotal evidence suggested that demand conditions improved amid greater client numbers.

    Survey respondents noted that where workforce numbers rose it was due to a rise in temporary workers. Greater new order inflows alongside little change in employment led to a renewed rise in backlogs during December.At the same time, inflationary pressures built further as overall input prices and output charges increased again at the end of the year. The rise in total operating expenses stemmed from higher purchase costs, as wage bills ticked down.

    However utility, construction material and sugar prices reportedly drove the latest increase in purchase costs. Companies sought to pass through higher input prices to customers via greater selling prices amid the accommodative demand conditions which is characteristic of the festive season. Meanwhile, input buying increased again at Ugandan businesses amid  greater new order inflows in December. Demand for items placed pressure on suppliers who saw lead times lengthen, but firms were able to accumulate stocks again, nonetheless.

    Output expectations for 2026 across the private sector are positive. There are hopes of stronger demand following investment in advertising and customer outreach which is reportedly underpinning the broad-based optimism.
  • Ugandan private sector continues to grow amid upturn in output in August

    Ugandan private sector continues to grow amid upturn in output in August

    Key findings

    Business activity and new orders expand further

    Employment rises again amid positive outlook for output

    Purchase and staff costs tick higher

    Ugandan companies registered a further expansion in business activity midway through the third quarter, extending the current sequence of growth to seven months as the headline Stanbic Bank Purchasing Managers’ Index (PMI) remained above the positive threshold mark of 50.0. At 53.3 during August, the Stanbic Bank PMI was down slightly from 53.6 in July, but maintained a trend of improving private sector conditions on a monthly basis since February.

    Christopher Legilisho, Economist at Stanbic Bank said, “The Stanbic Bank Uganda PMI showed ongoing strong economic conditions in the private sector in August. Sustained new order and output growth imply business conditions were supportive across all sectors. Furthermore, quantities of inputs purchased increased, and inventories grew. Meanwhile, companies were still optimistic about future output.”

    Christopher Legilisho

    He said, “Employment conditions were robust in August, except for manufacturing where staffing numbers were unchanged on the month. Inflationary pressures remained amid increases in total input prices, purchase costs and staff costs, with August headline CPI unchanged from July.”

    The Stanbic Bank PMI is compiled by S&P Global on behalf of Stanbic Bank Uganda, from responses to monthly questionnaires sent to purchasing managers. The sectors covered by the survey include agriculture, mining, manufacturing, construction, wholesale, retail and services.

    The PMI is a weighted average of the following five indices: New Orders (30%), Output (25%), Employment (20%), Suppliers’ Delivery Times (15%) and Stocks of Purchases (10%). During August, the Stanbic Bank PMI panelists said the upturn was due to stronger demand conditions and another round of new order growth. It was supported by increases in output, new orders, employment and inventories. Upbeat projections for business activity over the coming year also underpinned growth in input buying.

    Meanwhile, job creation and greater capacity enabled firms to stay on top of their backlogs of work. At the same time, further increases in purchase and staff costs pushed overall input prices up. Favourable demand conditions allowed firms to pass on higher costs to customers via another rise in selling prices. New sales also rose for a seventh month running in August. The increase was attributed by firms to successful advertising and marketing campaigns. At the sector level, expansions in both output and new orders were recorded in all segments. Companies also supported the processing of new orders through greater input buying and efforts to build safety stocks. As a result, backlogs of work were depleted for the seventh time in the last eight months and vendor performance was broadly unchanged on the month. Although decreases in total input prices were recorded in the agriculture and construction sectors, the rise in output charges was broad-based by segment.

    Meanwhile, output expectations at Ugandan companies remained positive in August, as firms foresee a rise in business activity in the coming year. Confidence was reportedly buoyed by planned investment in advertising and client outreach.

  • Stanbic PMI: Private sector performance continues to improve in March

    Stanbic PMI: Private sector performance continues to improve in March

    Key findings

    Growth in output and new orders sustained

    Job creation persists amid continued optimism in the outlook

    Higher input costs spur further rise in selling prices

    Strong demand conditions drove growth in input buying, as firms stocked up amid anticipation of more upturns in activity later in the year, slightly lifting the monthly Stanbic Purchasing Managers’ Index (PMI).

    The headline Stanbic PMI rose to 52.9 during March, up from 52.6 in February. The latest data indicated back-to-back improvements in the health of the Ugandan private sector for the second month running. There were also further increases in output, new orders and employment.

    Christopher Legilisho, Economist at Stanbic Bank said, “The March PMI for Uganda confirmed a private sector with still sound consumer demand aiding growth in output, new orders, employment, and inventories. All sectors surveyed displayed broad-based growth in activity on average in Quarter One (Q1) 2025. Further, firms remained optimistic about the economic outlook, foreseeing sustained consumer demand over the coming year.”

    Christopher Legilisho

    The monthly survey is compiled by S&P Global from responses to questionnaires sent to about 400 purchasing managers. The sectors covered by the survey include agriculture, mining, manufacturing, construction, wholesale, retail and services.

    It is a weighted average of the following five indices: New Orders (30%), Output (25%), Employment (20%), Suppliers’ Delivery Times (15%) and Stocks of Purchases (10%). Readings above 50.0 signal an improvement in business conditions on the previous month, while readings below 50.0 show deterioration.

    New business received by Ugandan companies increased again, as panelists highlighted new customer acquisitions and favourable demand conditions. However, inflationary pressures persisted as higher purchase and staff costs drove up overall input prices. Accommodative demand conditions enabled firms to continue raising their output charges.

    Legilisho said, “Rising input costs kept prices under pressure in March. Pricing strains were felt by firms as utility bills, shipping fees and commodity prices went up, while staff costs and output prices increased for a further month. Promising economic conditions allowed firms to pass on costs to consumers. The March PMI implies a sustained improvement in economic conditions in the private sector.”

    In line with a broad-based upturn in new orders, the five monitored sectors also recorded greater business activity at the end of the first quarter. Business confidence in the outlook for output over the coming 12 months remained upbeat in March. Optimism was reportedly underpinned by hopes of further improvements to the sales environment and new client wins.

    Subsequently, firms raised their staffing levels to accommodate greater new order inflows and anticipated growth in output in the coming months. All five monitored sectors registered higher staffing levels, with some respondents mentioning this was largely due to the hiring of temporary workers.

    Nonetheless, increased capacity following job creation enabled firms to deplete their backlogs of work for a third month running in March.

    At the same time, Ugandan businesses stated that higher utility, raw material and staffing costs led to a broader rise in operating expenses in March. Purchase prices and wage bills rose again on the month.

    In response to higher costs, companies raised their output charges for the seventh month running. An upbeat sales environment enabled firms to pass on greater input prices to clients.

    In line with a rise in new orders, Ugandan firms expanded their input buying and sought to build safety stocks. There was a fresh increase in pre-production inventories during March, aided by a further improvement in suppliers’ delivery times.